Asia contains several of the world's largest urban economies and some of its most influential financial centers. But Tokyo, Singapore, Hong Kong, Shanghai, Beijing, Dubai, Seoul, and Macau are rich in fundamentally different ways.
Tokyo and Seoul draw strength from industrial and technology networks. Shanghai and Beijing reflect the scale of China's domestic market. Singapore and Hong Kong serve international finance. Dubai has grown through trade, services, and a pro-business environment. Macau illustrates the opportunities and risks of a highly specialized economy.
This guide compares these eight cities using publicly reported economic activity, financial infrastructure, income data, and institutional frameworks. The cities are presented as a useful editorial selection, not as an exact ranking of private fortunes.
What counts as urban wealth?
No single measure establishes which city is “the richest.” GDP measures production, not the wealth owned by households. GDP per capita is sensitive to jurisdictional boundaries and commuting patterns. Household income better captures local earnings but does not include every financial asset. High property values show scarcity and demand but can coexist with affordability problems.
Our approach therefore keeps these dimensions separate:
Size of the economy and its principal industries.
Resident living standards, using published government income and employment statistics.
Financial infrastructure, including exchanges, regulated institutions, and asset-management activity.
Investment and international connectivity, as reflected in business activity and economic policy.
Practical considerations for internationally mobile residents, such as costs, taxes, and lawful immigration pathways.
We do not rank cities using undocumented estimates of local millionaire populations or percentages. These figures can vary sharply with the definition of assets, household membership, residence, and geographic boundaries.
1. Tokyo, Japan: the corporate and industrial giant
Tokyo is central to Japan's manufacturing, financial, technology, and service industries. Its metropolitan area supports headquarters functions for major global companies, large consumer markets, and sophisticated transport and professional infrastructure. The Tokyo metropolitan government and Japan's Statistics Bureau publish economic and demographic indicators that make those strengths visible.
Tokyo's appeal is not limited to financial markets. It combines business infrastructure, transport networks, safety, higher education, and broad employment opportunities. These factors help explain why companies maintain operations in the region even when growth in Japan's overall population is slow.
For international entrepreneurs, immigration and tax rules are important. Japan has multiple status-of-residence categories for work and business, each with conditions that can change. The income, inheritance, and gift-tax consequences of residence can be material and depend on personal circumstances. There is no basis for treating Tokyo's economic scale as proof of a particular millionaire population.
2. Singapore: wealth management and regional headquarters
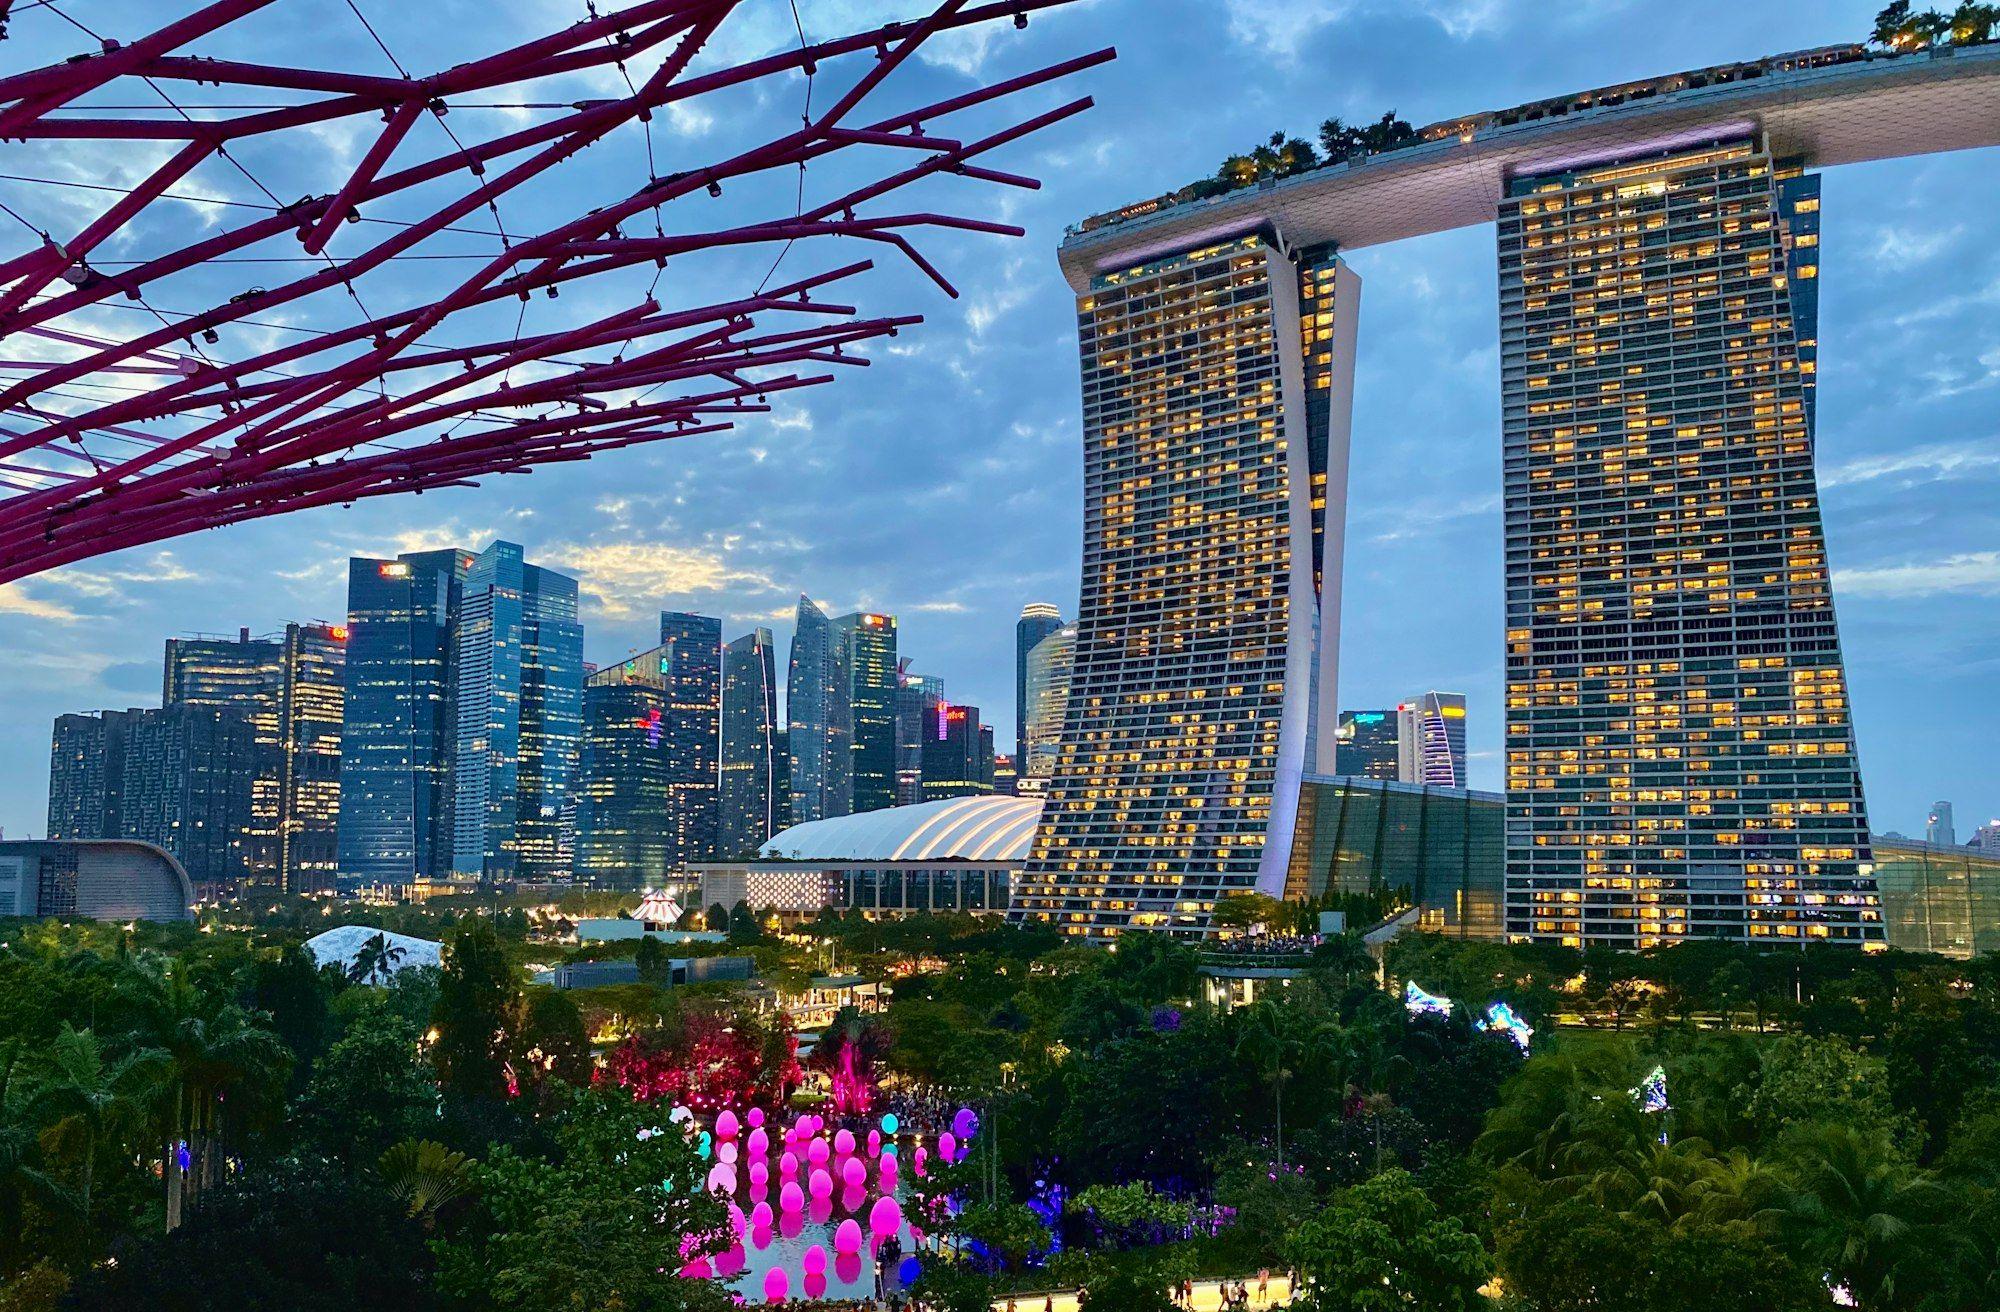
Singapore combines financial regulation, logistics, technology, law, and regional corporate activity within a single city-state. That makes its economic boundaries clearer than those of many metropolitan regions. Singapore's Department of Statistics reports production, employment, and household income; the Monetary Authority of Singapore reports on the asset-management industry.
The financial ecosystem is observable through regulated financial institutions, fund-management activity, and businesses supporting international capital. Singapore's success does not need to be asserted through an unverifiable estimate of how many residents are worth more than a million dollars.
For families and businesses, the attraction includes reliable infrastructure, widespread use of English, and access to Southeast Asian markets. Trade-offs include expensive housing, selective immigration, and substantial property-purchase duties for many foreigners. Singapore generally does not tax personal capital gains, but this is not an exemption for every payment, trade, or income stream, and specific facts can change the tax treatment.
The Global Investor Programme is a selective permanent-residence pathway for applicants meeting official criteria. Permanent residence does not guarantee Singaporean citizenship. Any published investment thresholds should be verified with the Singapore Economic Development Board before an application.
3. Hong Kong: a bridge to international capital
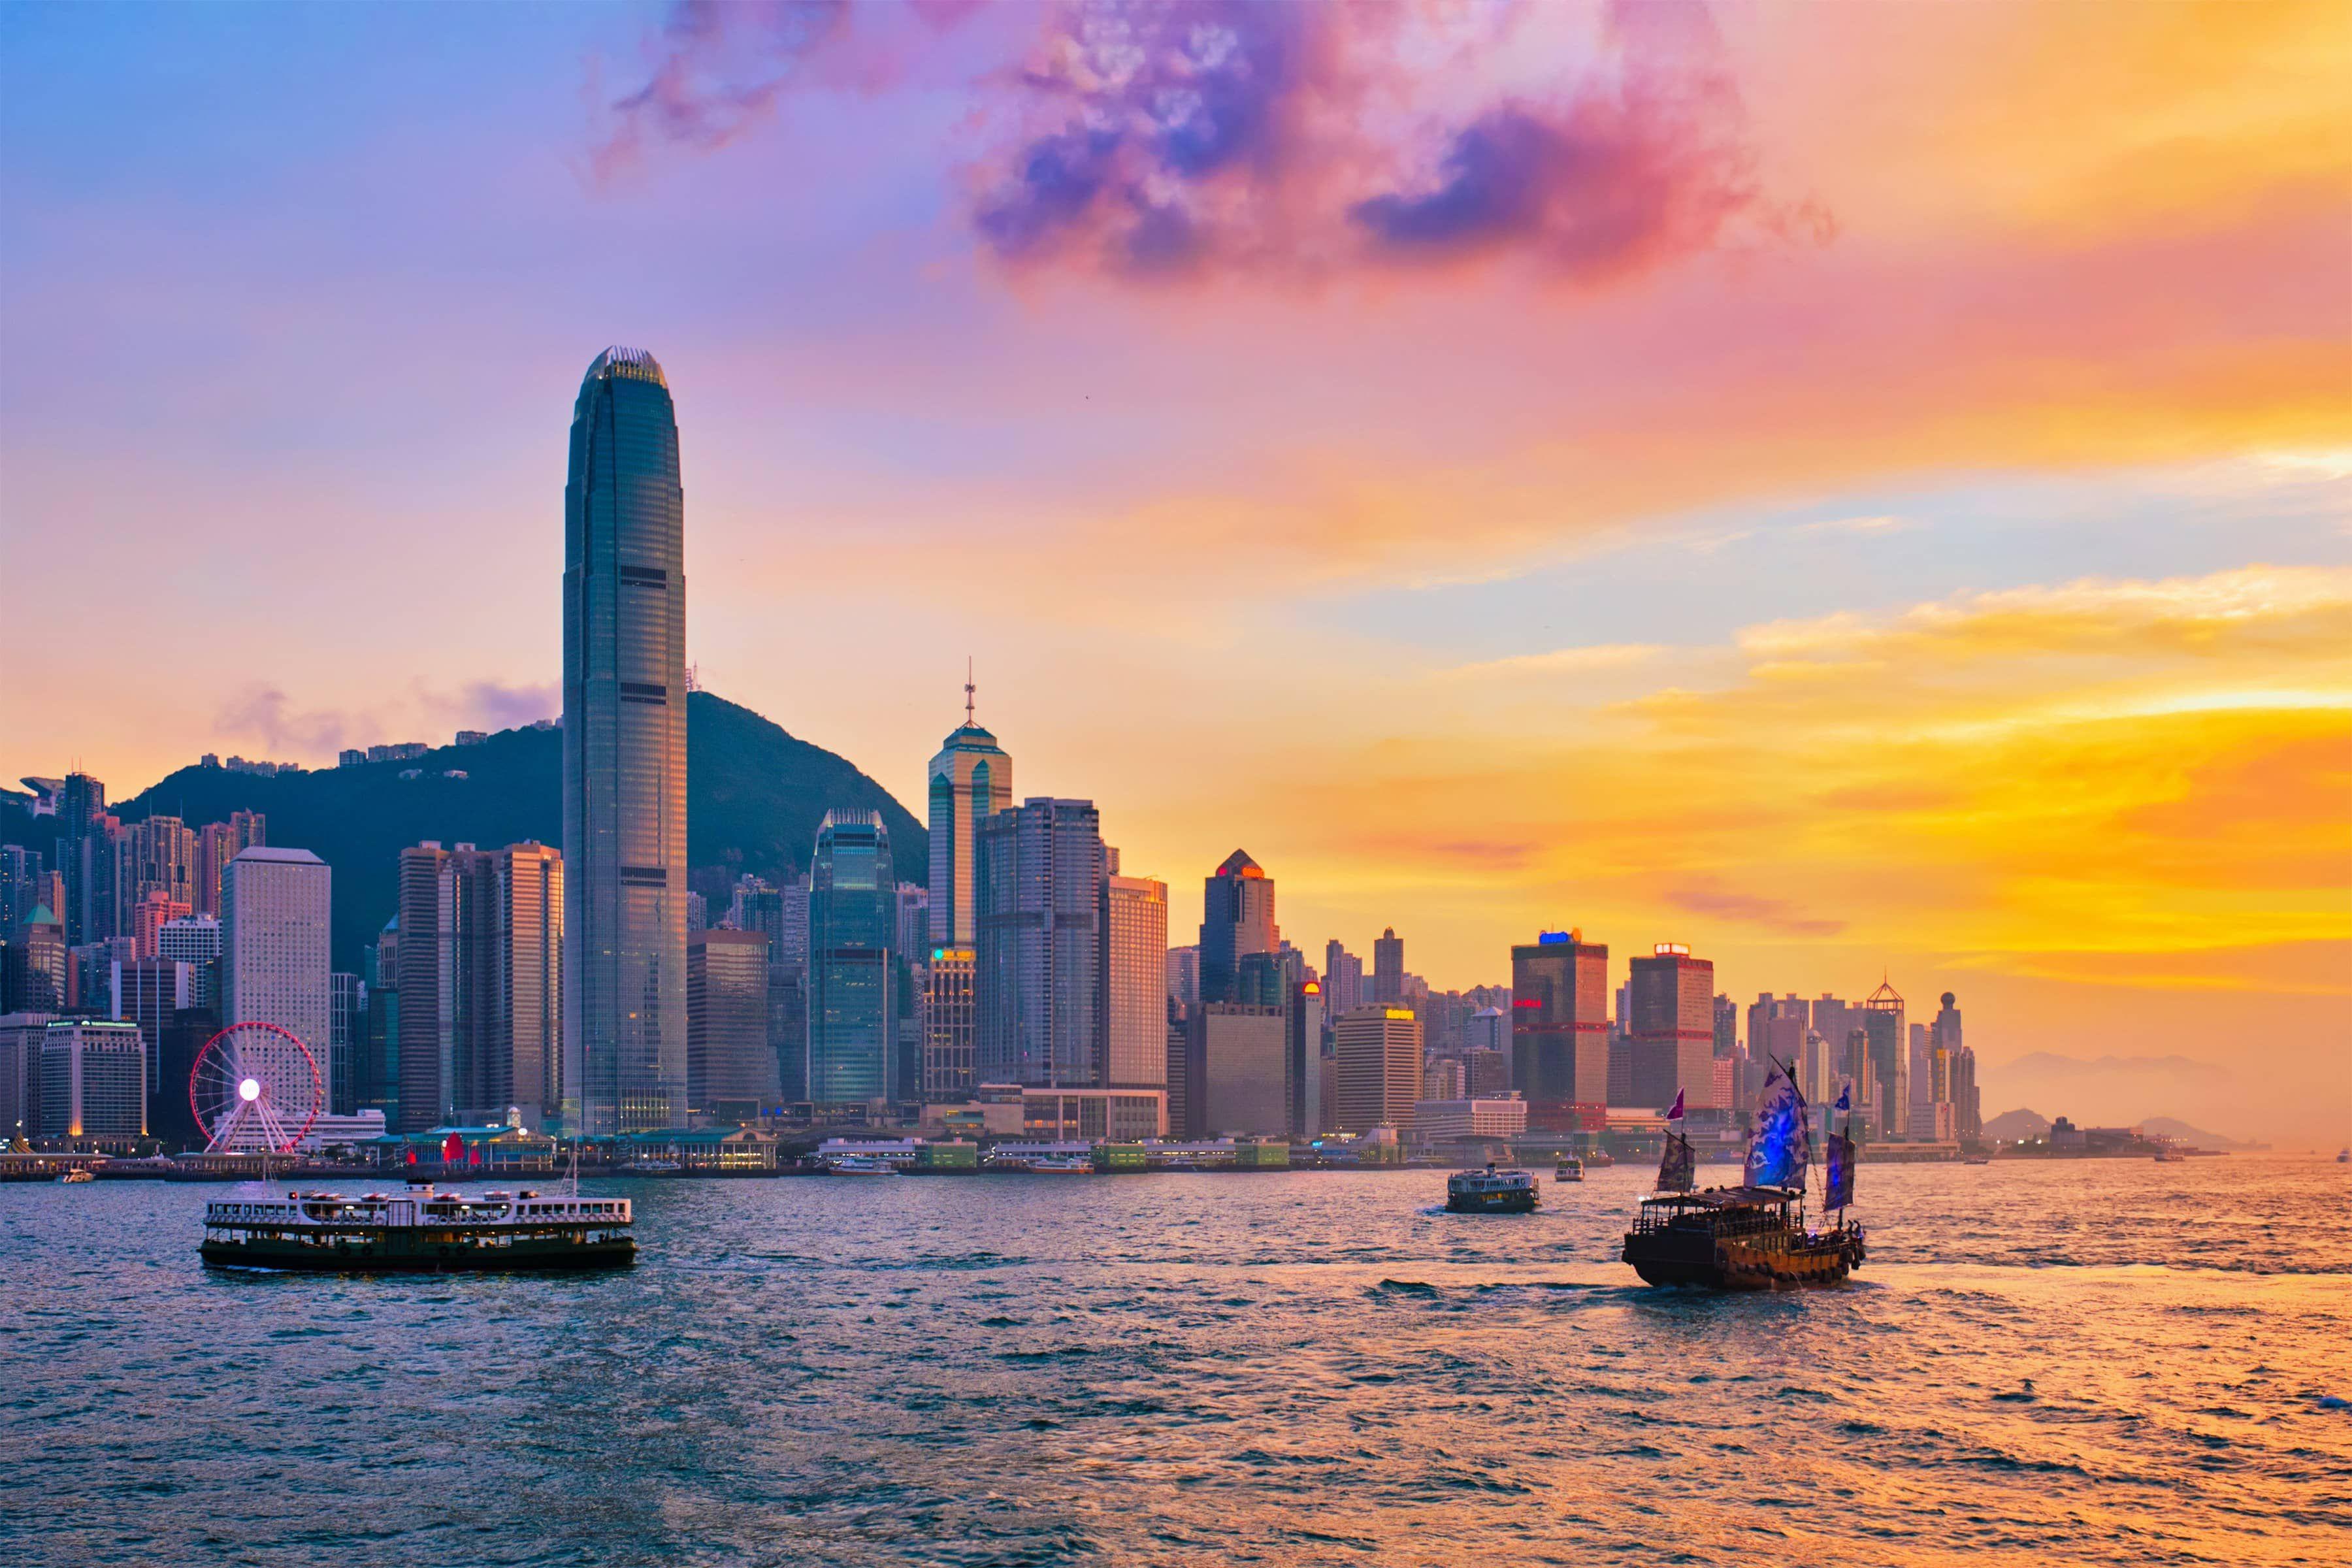
Hong Kong's position rests on capital markets, financial services, logistics, professional services, and its connections with mainland China. The Hong Kong Census and Statistics Department publishes detailed economic and household indicators, while the Hong Kong Exchanges and Clearing group reports financial-market activity.
Its taxation system differs from those of many other international financial centers, including a territorial framework for key categories of income. That can be attractive to businesses, but the interpretation of income source and the treatment of individual transactions require careful advice.
Hong Kong's New Capital Investment Entrant Scheme and talent-related admission routes offer immigration options for qualifying individuals. These routes should be evaluated on their current official rules and the rights they actually confer. Neither the performance of the stock market nor high property prices can be turned into an unverified count of resident millionaires.
4. Shanghai: commercial scale and financial markets
Shanghai is one of mainland China's largest commercial and financial centers. Manufacturing, trade, transport, technology, financial services, and corporate headquarters activities all play a role in its economy. The Shanghai Municipal Statistics Bureau publishes regional figures, and the Shanghai Stock Exchange provides information about listed companies and market activity.
Shanghai's port and logistics infrastructure connect Chinese production to global markets. Its finance and technology sectors are closely linked to national economic policy and regulatory priorities. For international businesses, that creates both opportunities and compliance requirements.
Nominal GDP comparisons between Shanghai and cities in other countries must account for exchange rates, price levels, and the precise territorial definition. A high level of output does not measure the net worth of its residents.
5. Beijing: headquarters, research, and policy
Beijing combines political institutions, leading universities, research organizations, technology companies, and headquarters functions for large domestic businesses. Its economy benefits from knowledge-intensive services and close links between research and industry.
The Beijing Stock Exchange and official municipal statistics provide measurable indicators of business and capital-market activity. Yet even strong technology clusters do not translate directly into household asset balances. Company valuations change, and not every employee or founder owns liquid shares.
For entrepreneurs, access to the Chinese domestic market, research talent, and institutional relationships may outweigh tax advantages available in other locations. Foreign investment rules and lawful residence options require sector-specific and individual review.
6. Dubai, United Arab Emirates: commerce and a growing financial center
Dubai sits geographically in western Asia and is an important connector between Asian, African, and European markets. It has built businesses around aviation, logistics, hospitality, trade, real estate, technology, and financial services.
The Dubai International Financial Centre's official 2025 results, issued in February 2026, reported 8,844 active companies, 1,052 regulated firms, and more than 500 wealth and asset-management companies. These numbers are useful precisely because they refer to operating institutions, not estimated personal fortunes.
The UAE does not generally tax personal employment income, but it applies VAT and corporate-tax rules. Free-zone tax conditions must be satisfied where relevant. Dubai's Golden Visa offers renewable long-term residence to certain eligible people, not guaranteed naturalization or universal tax exemption. International families must still consider tax and citizenship obligations in other jurisdictions.
7. Seoul, South Korea: advanced industry and research
Seoul is the center of a sophisticated industrial and services economy, with major strengths in electronics, automotive technology, telecommunications, software, media, and finance. Public statistics from Statistics Korea and the Seoul city government provide information on incomes, production, population, and employment.
The wider capital region benefits from manufacturing and research networks that extend beyond Seoul's administrative boundaries. Comparing Seoul city proper against an entire foreign metropolitan region can produce an unfair GDP comparison; geographic definitions must be stated.
Korea offers residence routes for qualifying professionals, entrepreneurs, and investors, but their conditions and required commitments differ. Investors should also consider taxation, housing costs, and potential economic exposure to export cycles. Seoul's technological capability provides stronger evidence of economic importance than a guessed number of local high-net-worth residents.
8. Macau: a specialized visitor economy
Macau is unusual because tourism and gaming have had a disproportionately large role in its economy. The Government of Macao's Statistics and Census Service publishes detailed figures on GDP, visitors, and sector activity, allowing readers to understand the territory's economic cycles.
High output per person can reflect the size of a specialized industry relative to a small resident population. That does not mean an equivalent amount is owned or earned by every resident. Macau's vulnerability to shifts in visitor demand and gaming policy is an important part of any prosperity assessment.
Macau has also explored economic diversification, including conferences, cultural industries, and other business services. For international entrepreneurs, the market's small size, regulatory environment, and residence framework require particular attention.
How these cities differ
City
Primary economic strengths
Main trade-off to examine
Tokyo
Corporate headquarters, industry, finance
Demographics, taxes, and business-entry complexity
Singapore
Asset management, services, regional headquarters
Housing costs and selective immigration
Hong Kong
Capital markets and China connectivity
Policy, housing, and residence considerations
Shanghai
Manufacturing, trade, financial services
Regulatory exposure and economic cycles
Beijing
Research, technology, administration
Market access and regulatory complexity
Dubai
Trade, financial services, logistics
Residence rights and cross-border tax planning
Seoul
The comparison is qualitative because no consistent city-level private-wealth census exists for all eight. A table purporting to show the exact number of millionaires in each city would require a proprietary model and extensive methodological caveats.
Property markets are not household wealth
Some international city comparisons show how many square meters of luxury property a fixed US-dollar amount buys. Such figures can be useful for understanding prime residential markets, provided the underlying research, transaction dates, and property definitions are known. They should not be extrapolated into rankings of overall wealth or broad housing affordability.
To make better decisions, compare publicly published median prices, rents, mortgage conditions, transaction activity, and local earnings. National statistical agencies and government land departments are preferable starting points. Prime-market asking prices are not necessarily representative of what ordinary households pay.
Choosing a city for business, residence, or family life
An investment location is not automatically a good residence location. A fund manager may favor Singapore or Hong Kong for proximity to financial infrastructure. An exporter may favor Shanghai, Tokyo, or Seoul for industrial connections. A family may prioritize schooling, residency security, public safety, and lifestyle.
Second citizenship can complement, but does not replace, an appropriate residence and tax plan. CitizenX helps clients compare citizenship pathways as part of a broader strategy for international mobility and resilience.
Final thoughts
Asia's leading urban economies are rich in different resources: capital-market access, industrial capacity, human talent, commercial networks, or specialized services. Tokyo, Singapore, Hong Kong, Shanghai, Beijing, Dubai, Seoul, and Macau illustrate that variety.
The strongest comparison is one grounded in official data and clearly explained definitions, rather than an apparent precision about residents' private fortunes that the available public evidence cannot support.
Methodology note: These are eight illustrative economic centers, not an asset-based ranking. Statistics from different jurisdictions may refer to different years or geographic boundaries. Any tax or immigration guidance is general and should be checked against current law.